2025 Opportunities & Challenges for Private Equity under Trump

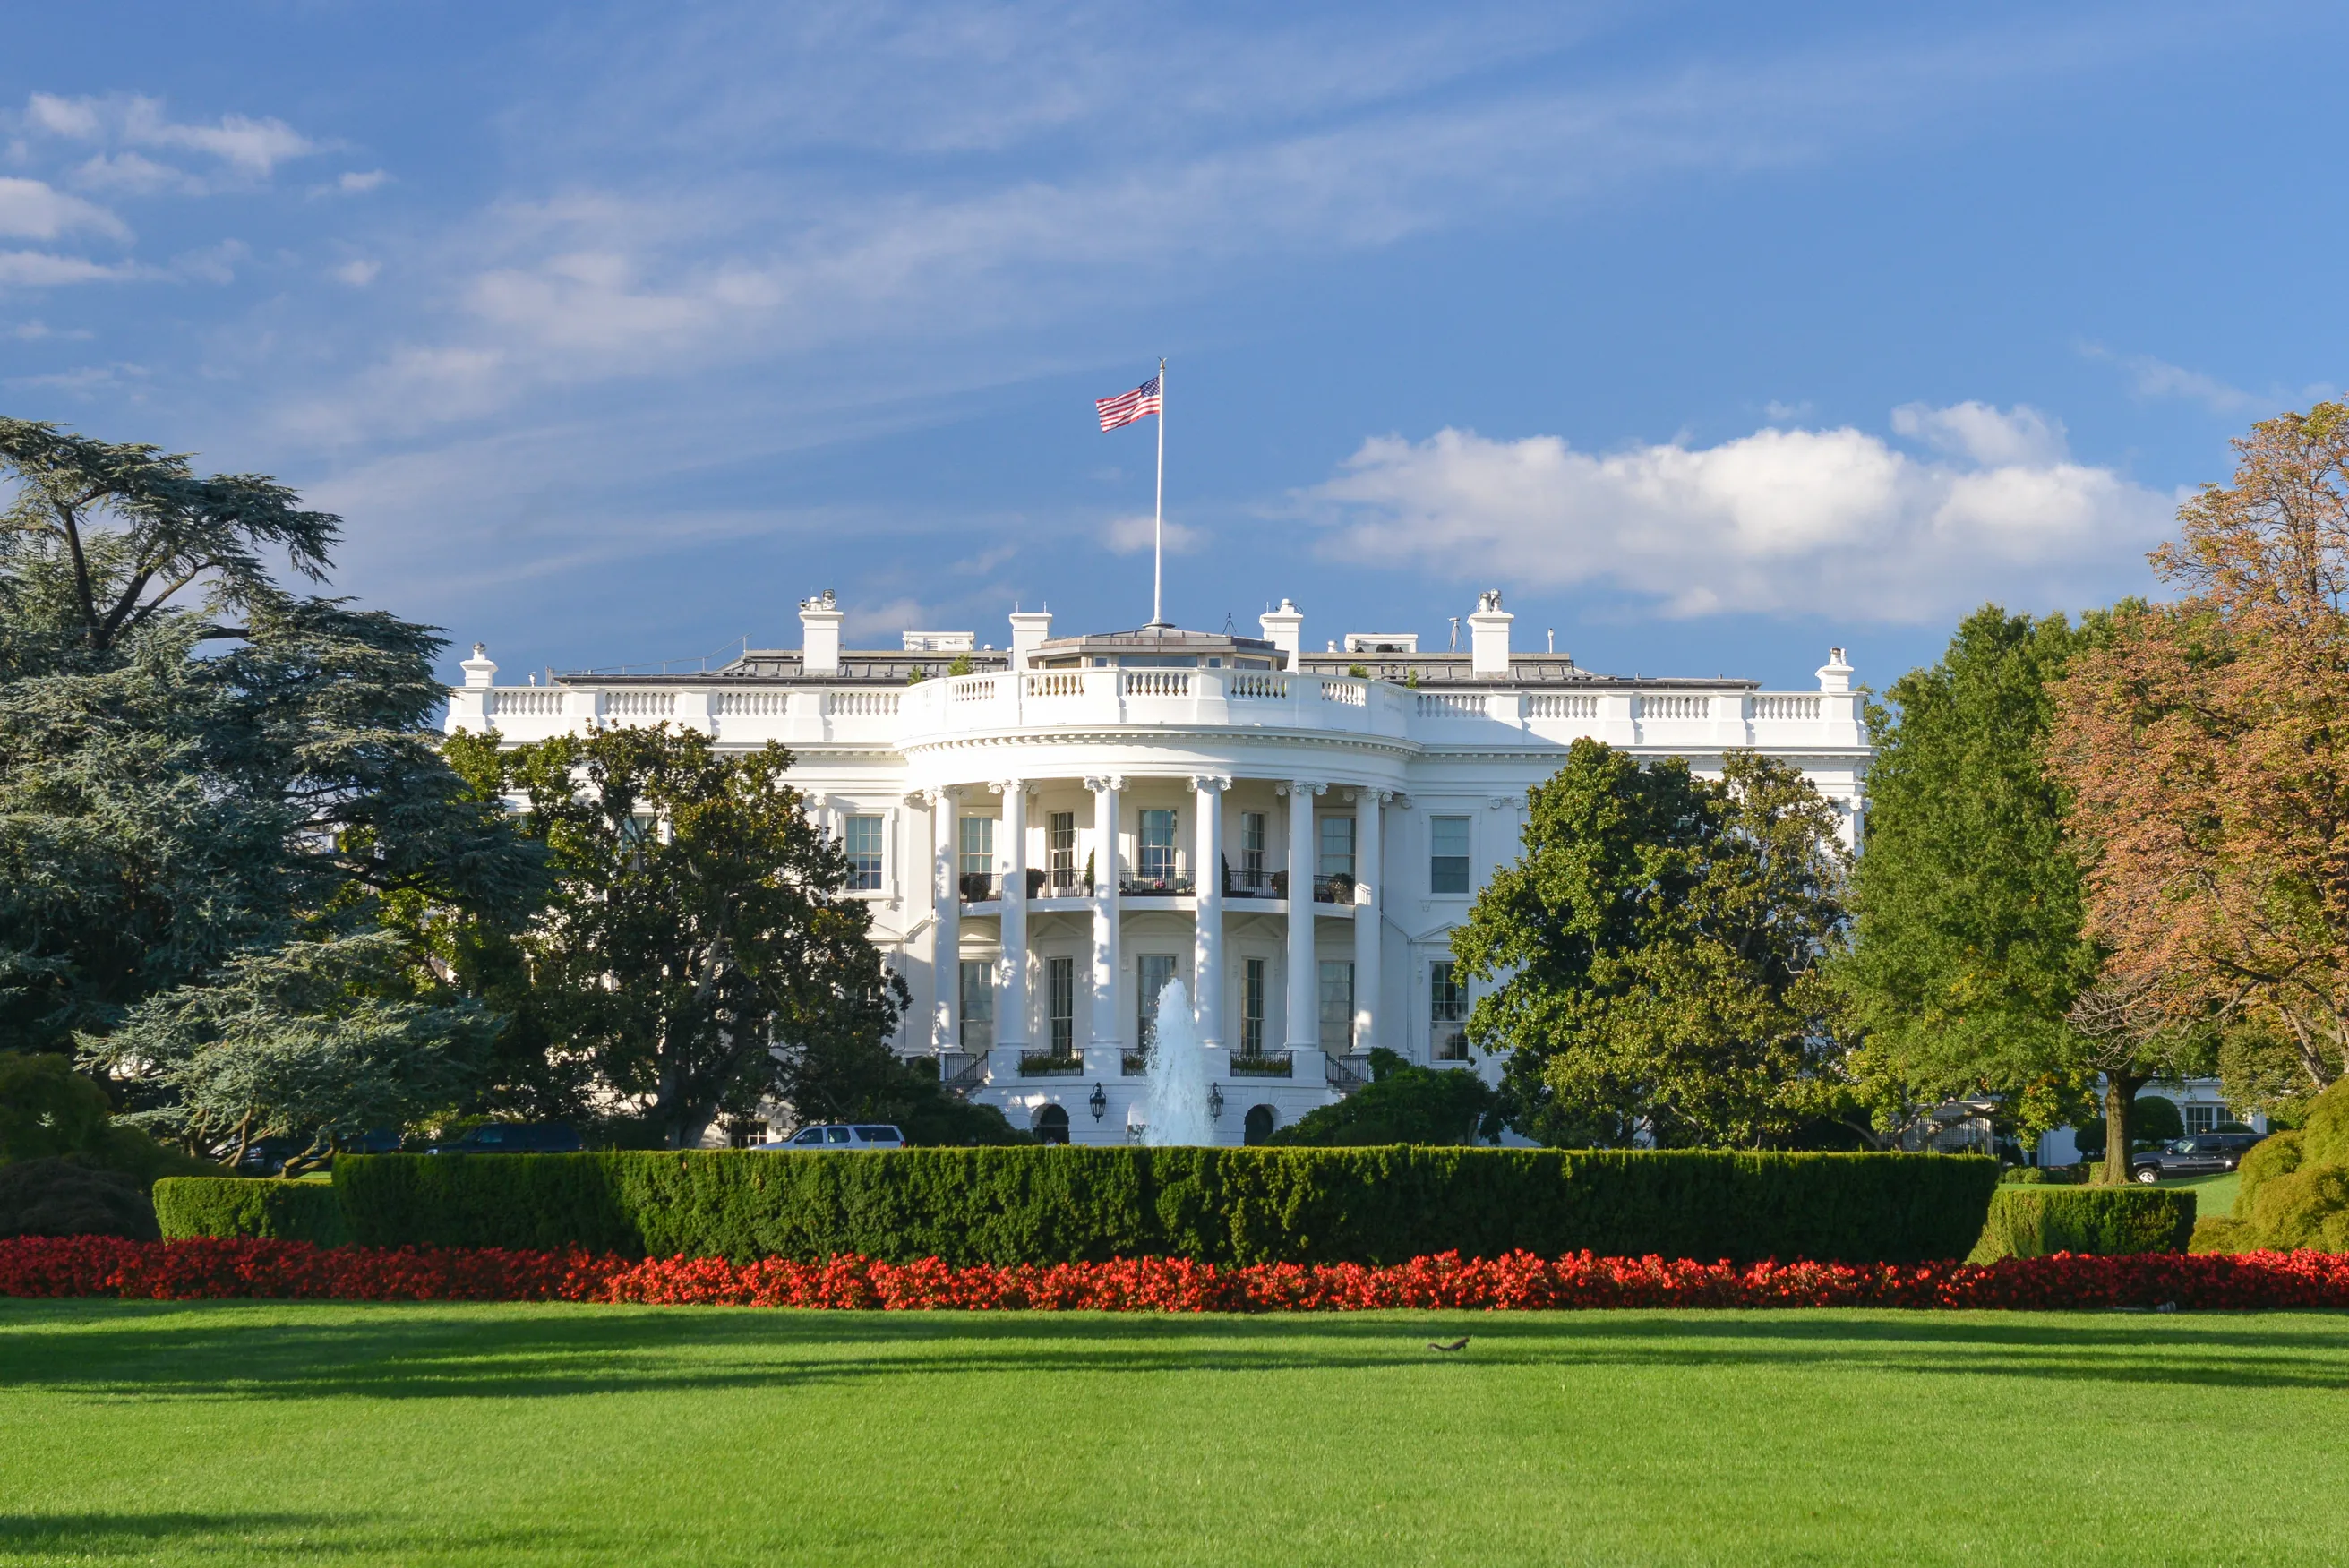
Well folks, it’s official: Donald Trump is back in the White House. It can be hard to make predictions for such a singular politician – but whatever one might think of him, it’s clear that his return is going to shake things up in a big way, the landscape for private equity and various high-growth industries being no exception. The political environment may be divisive, but the potential ramifications of his administration for PE firms seem clear. So, just what does this entail?
A hallmark of Trump’s first term was his focus onderegulationacross various industries, a trend expected to continue under his second term. For PE firms, fewer regulatory hurdles could mean faster, more flexible deal-making. This is particularly important in high-growth sectors such as AI, digital health, and life sciences, where the pace of innovation is often hindered by complex regulations. With less red tape, these industries could experience accelerated investment and development, offering PE firms the opportunity to back transformative technologies more swiftly. Furthermore, healthcare and energy sectors, including renewables, could also see nimbler M&A activity due to relaxed regulations.
Tax cutswere a prominent feature of Trump’s first administration, and they may be revisited in 2025. Reduced corporate tax rates could free up more capital for PE firms, allowing for greater investment capacity and expanded portfolios. These changes might potentially benefit firms by increasing after-tax returns and providing more room for reinvestment into growing businesses, acquisitions, or operations. Capital gains tax cuts could also improve returns on investments, providing a further boost to firms looking to drive profitability from early-stage investments and a lower cost basis on profitable exits.
Trump’s trade policies have historically leaned toward a more protectionist stance, with a focus on reshaping global trade dynamics. In 2025, this could present challenges such as tariffs or supply chain disruptions. However, for firms investing in U.S.-based high-growth sectors – especially tech, AI, and biotech – a stronger domestic focus could yield substantial opportunities. With more emphasis on reshoring manufacturing, AI research, or biotech development, PE firms focusing on U.S. innovation may find new value in areas like medical technology, cybersecurity, and green tech. These sectors could attract more U.S.-focused capital in response to trade tensions with other regions.
Trump’s administrations have been proponents of infrastructure investment, and in 2025, this could benefit PE firms looking to back long-term projects such as roads, energy grids, and telecommunications networks. The rising demand for tech infrastructure – driven by AI, where he has madesignificant investment, as well cloud computing, and 5G rollout – will likely attract PE investment as well. The expansion of smart cities and tech hubs could present new opportunities for investment in both physical infrastructure and digital infrastructure, such as data centres, autonomous vehicle infrastructure, and green energy solutions.
Trump’s first term saw historicallylow interest rates, which helped to fuel growth through debt financing. If the Federal Reserve continues to maintain accommodative policies under his second term, PE firms could benefit from low borrowing costs, making leveraged buyouts and debt-financed acquisitions more attractive. The ability to borrow cheaply could increase deal flow and make it easier for firms to scale their portfolios.
The possibility of further tax cuts or incentives under this administration could provide PE firms with more capital to allocate to high-growth investments. Whether in startups or mature companies, lower taxes could leave more room for reinvestment, allowing firms to expand operations, grow their portfolio, or pursue strategic acquisitions. The potential to improve after-tax returns is a key factor for private equity firms looking to maximise profits and scale their investments. This is particularly relevant for firms investing in research-heavy industries, such as digital health and life sciences, where the time to market for new products is longer but where there is considerable upside potential.
While global trade risks are always present, Trump's administration could make significant shifts in trade policies, affecting sectors with international exposure. However, in industries like tech, AI, and life sciences, many companies rely on a global talent pool and supply chains. With the right strategic approach, firms that specialise in these areas could continue to benefit from global collaborations in R&D and tech development. Moreover, with U.S. policies focused on fostering domestic technological innovation, these sectors could become even more attractive for PE firms seeking long-term, sustainable growth.
With Donald Trump back in the White House, the private equity landscape is likely to experience shifts that bring both challenges and opportunities. Deregulation, tax cuts, infrastructure investments, and low interest rates may create a favourable environment for deal-making and growth, particularly in high-growth sectors like tech, AI, digital health, and life sciences. While global trade dynamics may change, the opportunity for investment in these innovation-driven industries could prove to be significant.
Ultimately, the key for firms will be to stay agile, adapt to evolving policies, and seize the opportunities presented by these changes. Whether navigating deregulation or capitalising on domestic investments, firms that understand the implications of Trump’s return to the presidency could be well-positioned for continued success.
If you are curious about what the new political landscape might mean for your business – or if you wish to discuss talent and market trends for this year – pleasedrop me a line.
Tags:


- Insight
- Market Update
- Executive Search
With over 20 years of experience, Spencer leads the CFO and Finance Transformation practice at Venari Partners, partnering with CFOs, investors, and transformation leaders to build high-performing finance teams and deliver complex change programmes. He specialises in executive search and interim appointments across capital-intensive sectors, including life sciences, aviation, transport, infrastructure, industrials, and FMCG. Before moving into executive search, Spencer spent over a decade in general management, commercial and operational finance roles within the automotive and retail sectors, building and leading high performing teams, managing multi-million valued P&Ls and driving profitability through strategic improvements. He has also built and sold independent businesses, bringing a practical, entrepreneurial mindset to every client engagement. Based in Oxford with his young family, Spencer splits his time between London and international travel to meet clients and build long-term partnerships. Outside of work, he’s passionate about fitness, boxing, and classic cars, with a small collection of modern classics he enjoys tinkering with when he’s not busy being a dad to his two little girls.
View Full Profile